How to Measure Marketing Impact for Better Business Decisions
Explore
Summary
- Use consistent cost definitions, reporting periods, and forecast assumptions.
- Read measures together to identify questions that individual results cannot answer.
- Distinguish sales credited to advertising from additional sales it generated.
A marketing report can show improving results and still leave an important question unanswered: is there enough evidence to justify further investment? Marketing teams need to explain how the reported improvements support the case for increasing budget.
In global research published by Mastercard in April 2026, 73% of marketing leaders said uncertainty in measurement had affected their ability to justify spending to senior leadership.
This indicates that a clear connection between reported performance and what to do next is necessary. Our guide will help you establish that connection and reveal where further evidence is needed.
Set the Objective for Measuring Marketing Impact
Start with the business decision your report needs to inform. An organisation considering expansion needs to understand the value of new customers relative to acquisition costs. Where cash flow is a priority, the time required to recover those costs becomes especially relevant.
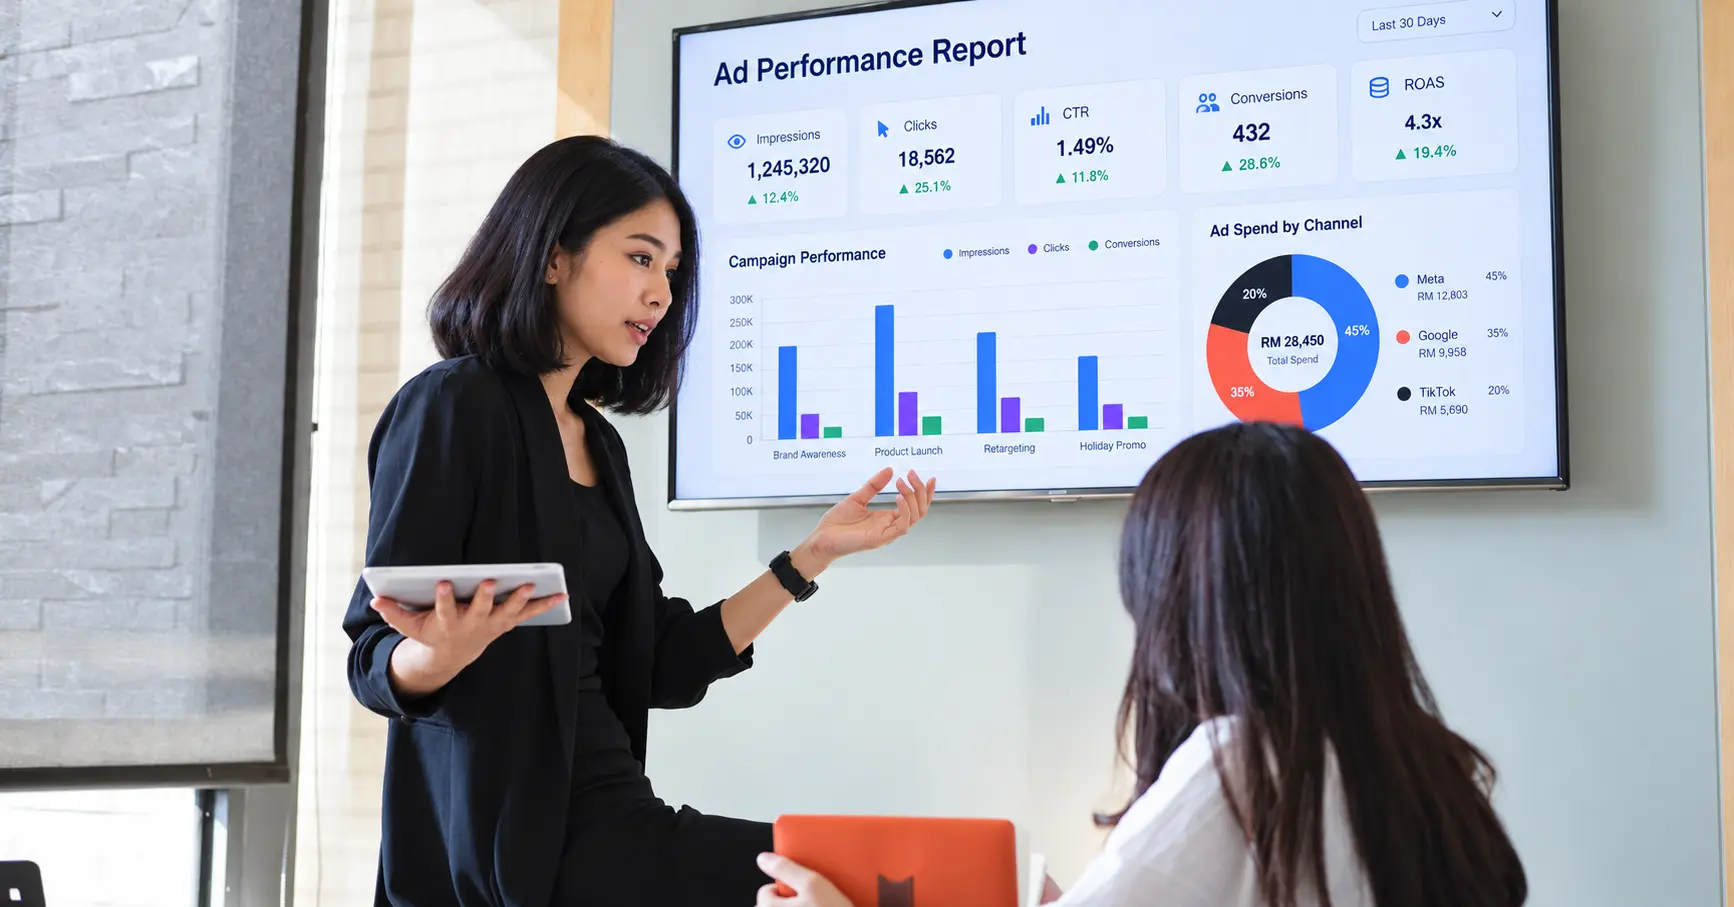
This also means agreeing on what “return” represents. When calculated using revenue, return on ad spend (ROAS) compares attributed revenue with advertising spend. Return on investment (ROI) considers profit relative to the investment.
Both measures can inform a review, but they answer different questions. When deciding whether to increase the budget, look beyond ROAS to assess whether the returns cover the relevant costs.
Define Your Marketing Metrics
Measure | Calculation | Interpretation and Limits |
|---|---|---|
Customer Acquisition Cost (CAC) | Acquisition-related sales and marketing costs ÷ new paying customers acquired |
|
Customer Lifetime Value (LTV) | Simplified gross-profit estimate: average annual revenue per customer × gross margin × expected customer lifespan in years |
|
Acquisition Payback Period | CAC ÷ average monthly gross profit per acquired customer |
|
Customer Retention Rate | Customers retained from the original group ÷ original group size × 100 |
|
Keep the Inputs Consistent
The calculations become more useful when marketing teams agree on how to apply them:
- Define the cost basis
Calculate gross profit using revenue after discounts and refunds, less the cost of goods or services delivered. Other operating expenses still need to be covered.
- Align the periods
Allow for delays between acquisition spending and completed sales. Monthly reviews can track progress, but the assessment should reflect the buying cycle. Compare customer groups over equivalent periods since acquisition.
- Separate results from forecasts
Label value already generated separately from expected future value, and state the assumptions behind each forecast.
These conventions help prevent differences in calculation from being mistaken for changes in performance. Where gaps in web or app tracking make comparisons difficult, the analytics support available through GrowthOps’ Performance Marketing and Analytics services can help strengthen the data informing the review.
How to Interpret Marketing Metrics Together
When measuring the impact of marketing, use the following questions to analyse changes in performance.
Acquisition Costs Are Falling. Are Customers Staying?
A lower CAC is more encouraging when customers continue purchasing and generating gross profit. Compare retention and gross profit across customer groups to understand whether lower acquisition costs are accompanied by sustained customer value.
If acquisition costs fall while retention weakens, investigate whether customer needs, promotional offers, or the experience after purchase have changed. A campaign may attract more first-time buyers without attracting customers who continue purchasing.
These comparisons identify patterns to investigate; they do not establish what caused them.
Lifetime Value Looks Strong. How Much Is the Forecast?
A promising LTV estimate may depend on customers continuing to purchase for several years. Before using it to justify further acquisition spending, check whether recent customer groups are behaving in line with those expectations.
If the business has limited purchase history, assess how a shorter customer relationship, lower purchase frequency, or reduced margin would affect the estimate. This shows how much the investment case depends on assumptions that remain unproven.
Revenue Is Growing. How Quickly Are Acquisition Costs Recovered?
Revenue growth does not necessarily mean acquisition costs are being recovered sooner. Discounts or higher delivery costs may reduce the gross profit available from each sale.
Check whether new customers are generating enough gross profit to cover acquisition costs sooner. A longer payback period can place greater demands on cash flow, even when sales are increasing. That makes payback relevant to both the amount and the timing of further investment.
Advertising Reports Strong Sales. What Evidence Shows Additional Sales?
Attributed sales are credited to advertising under a reporting model. Some customers may have purchased without that advertising, so the reported total does not establish how many additional sales it generated.
A carefully designed conversion lift test compares purchases between a group shown the advertising and a control group where it is withheld. This helps estimate how many extra sales the advertising generated. Consider the uncertainty around the estimate before acting. An inconclusive result calls for further investigation, rather than a firm conclusion that advertising had no effect.
Use Marketing Measurement to Guide Investment Decisions
Close each performance review with a recommendation that marketing and finance can assess together. Make clear:
- What changed: Identify the findings that matter to the decision.
- What remains uncertain: Explain any data gaps, forecast assumptions, or limits to attribution.
- What action is proposed: Specify the investment decision or investigation the findings support.
- When to review it: Set a review date that allows enough time for meaningful results to emerge.
At the next review, compare the results with expectations and decide whether to continue or adjust the approach. Over time, this process helps teams make investment decisions with a clearer understanding of the likely returns and the uncertainty that remains.